Investment Migration for
American Citizens.
How Americans use citizenship and residency by investment: tax-residency strategy, FATCA + GILTI considerations, second-passport options that work alongside US citizenship.
- United States passport rank:
- #7
Common motivations
- 1
Tax-residency optimisation — exit US tax exposure through documented relocation
- 2
Second passport for travel mobility outside US-political-status-sensitive jurisdictions
- 3
Family-mobility planning across multiple generations
- 4
Plan-B residency in case of policy or political shifts
American clients typically arrive at investment migration with one of three motivations: travel-mobility (a passport that doesn't carry US politics into immigration queues), tax-residency optimisation (substance-based relocation while retaining or renouncing US citizenship), and multi-generational planning (EU rights for children and grandchildren). Each motivation maps to a different stack. Travel-mobility is usually a Caribbean CBI — fast, no relocation required, $250K all-in. Tax positioning is UAE Golden Visa with documented substance, often paired with a Caribbean second passport for the mobility hedge. EU rights for descendants is Portugal Golden Visa (5-year naturalisation) or Malta CBI (direct citizenship). The decision matrix is usually narrowed in the first 60 minutes of a senior-advisor consultation: renouncement candidates and high-substance relocators want Malta or UAE; everyone else wants the Caribbean.
Best fits for American citizens

UAE

Portugal

St. Kitts & Nevis
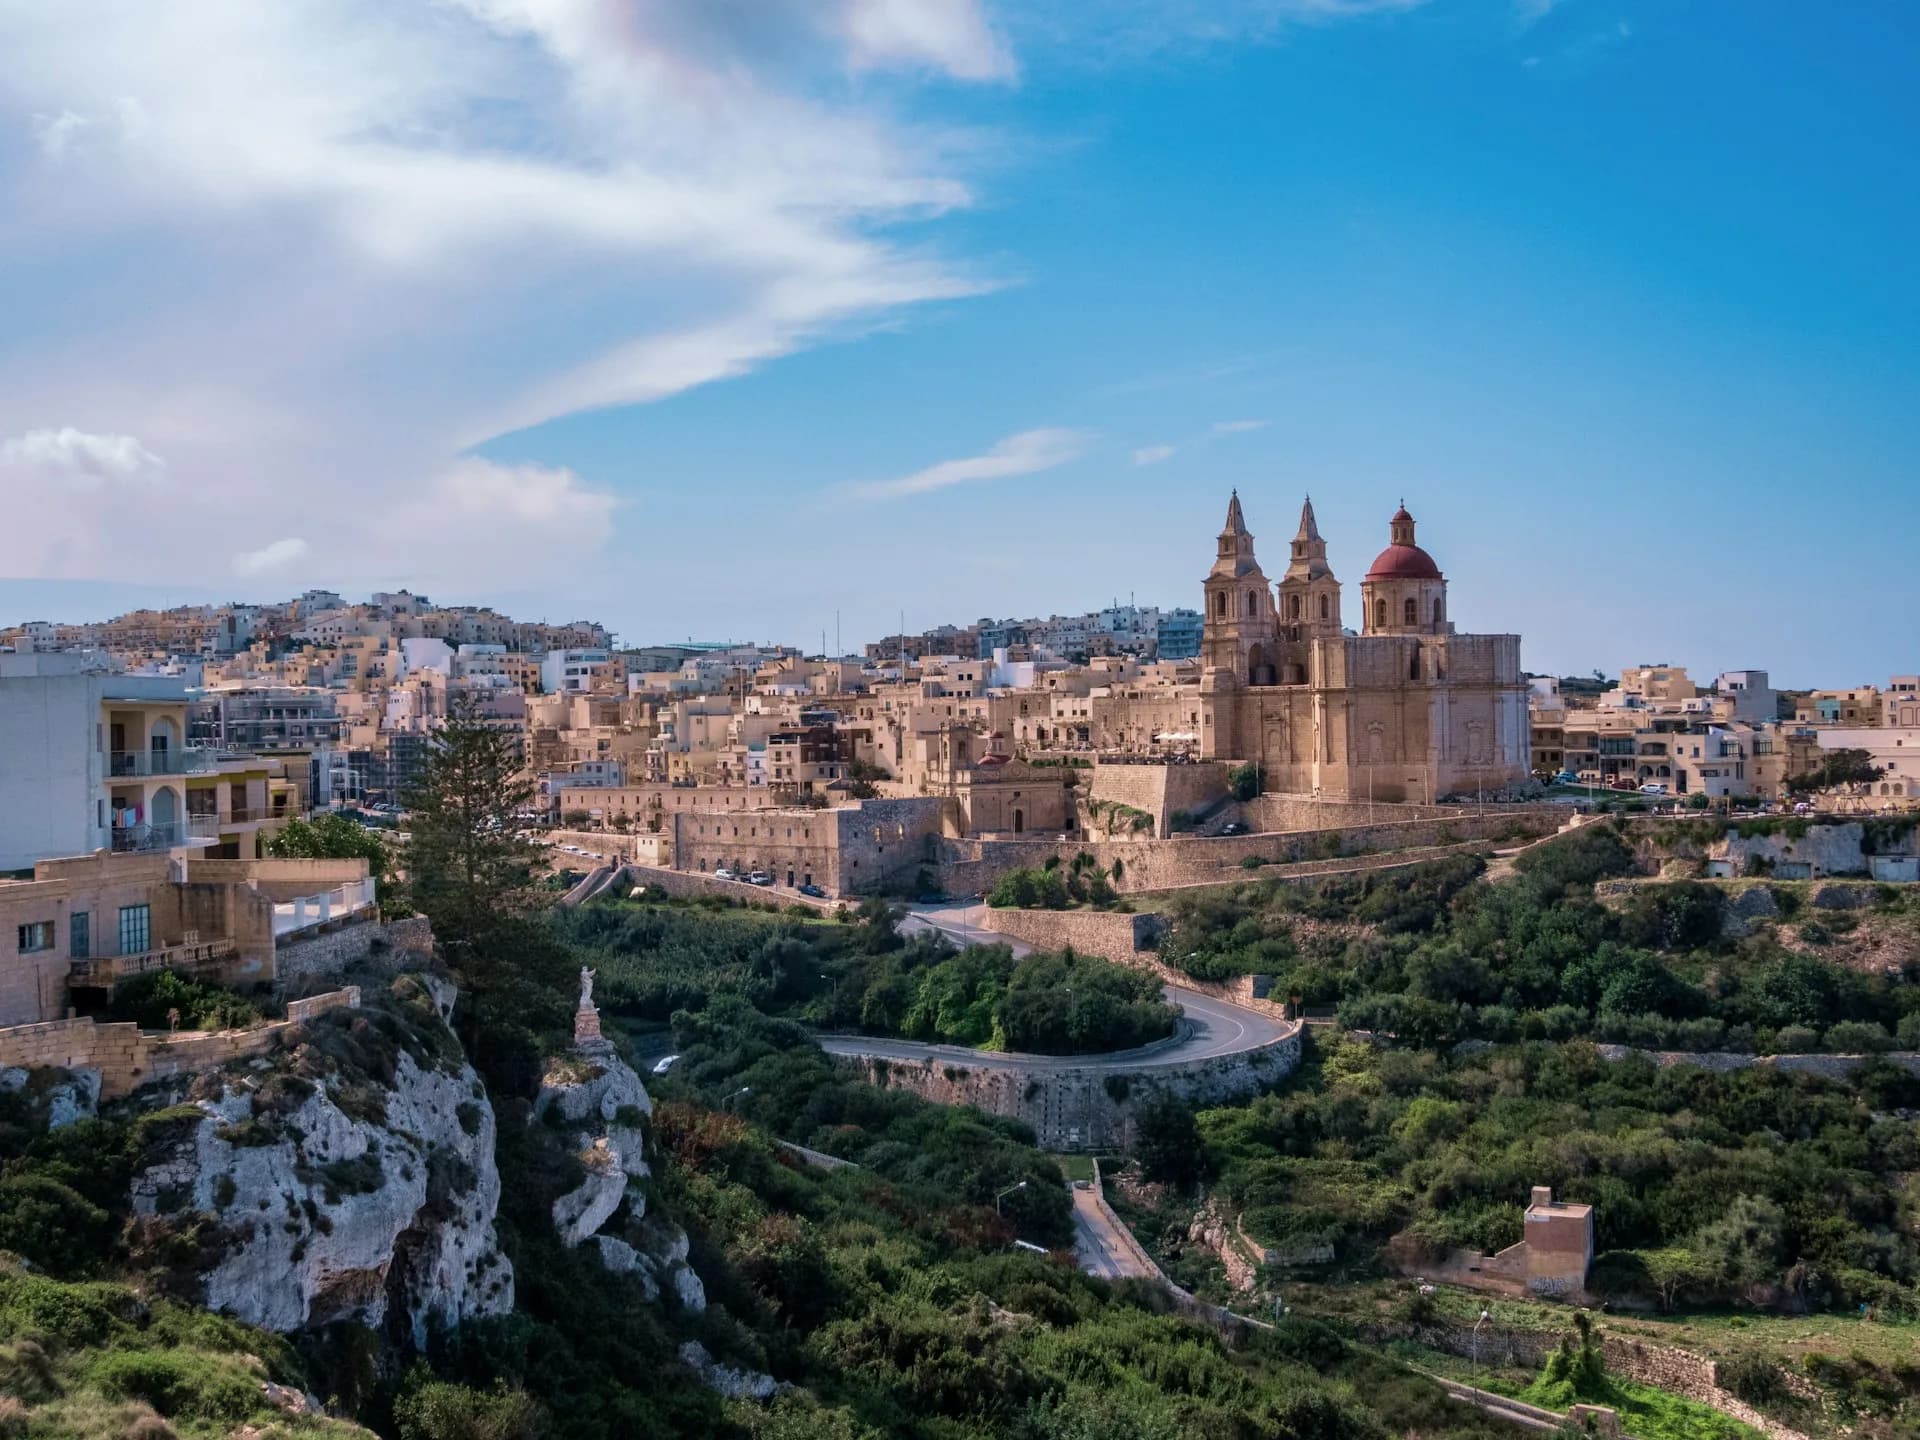

Malta
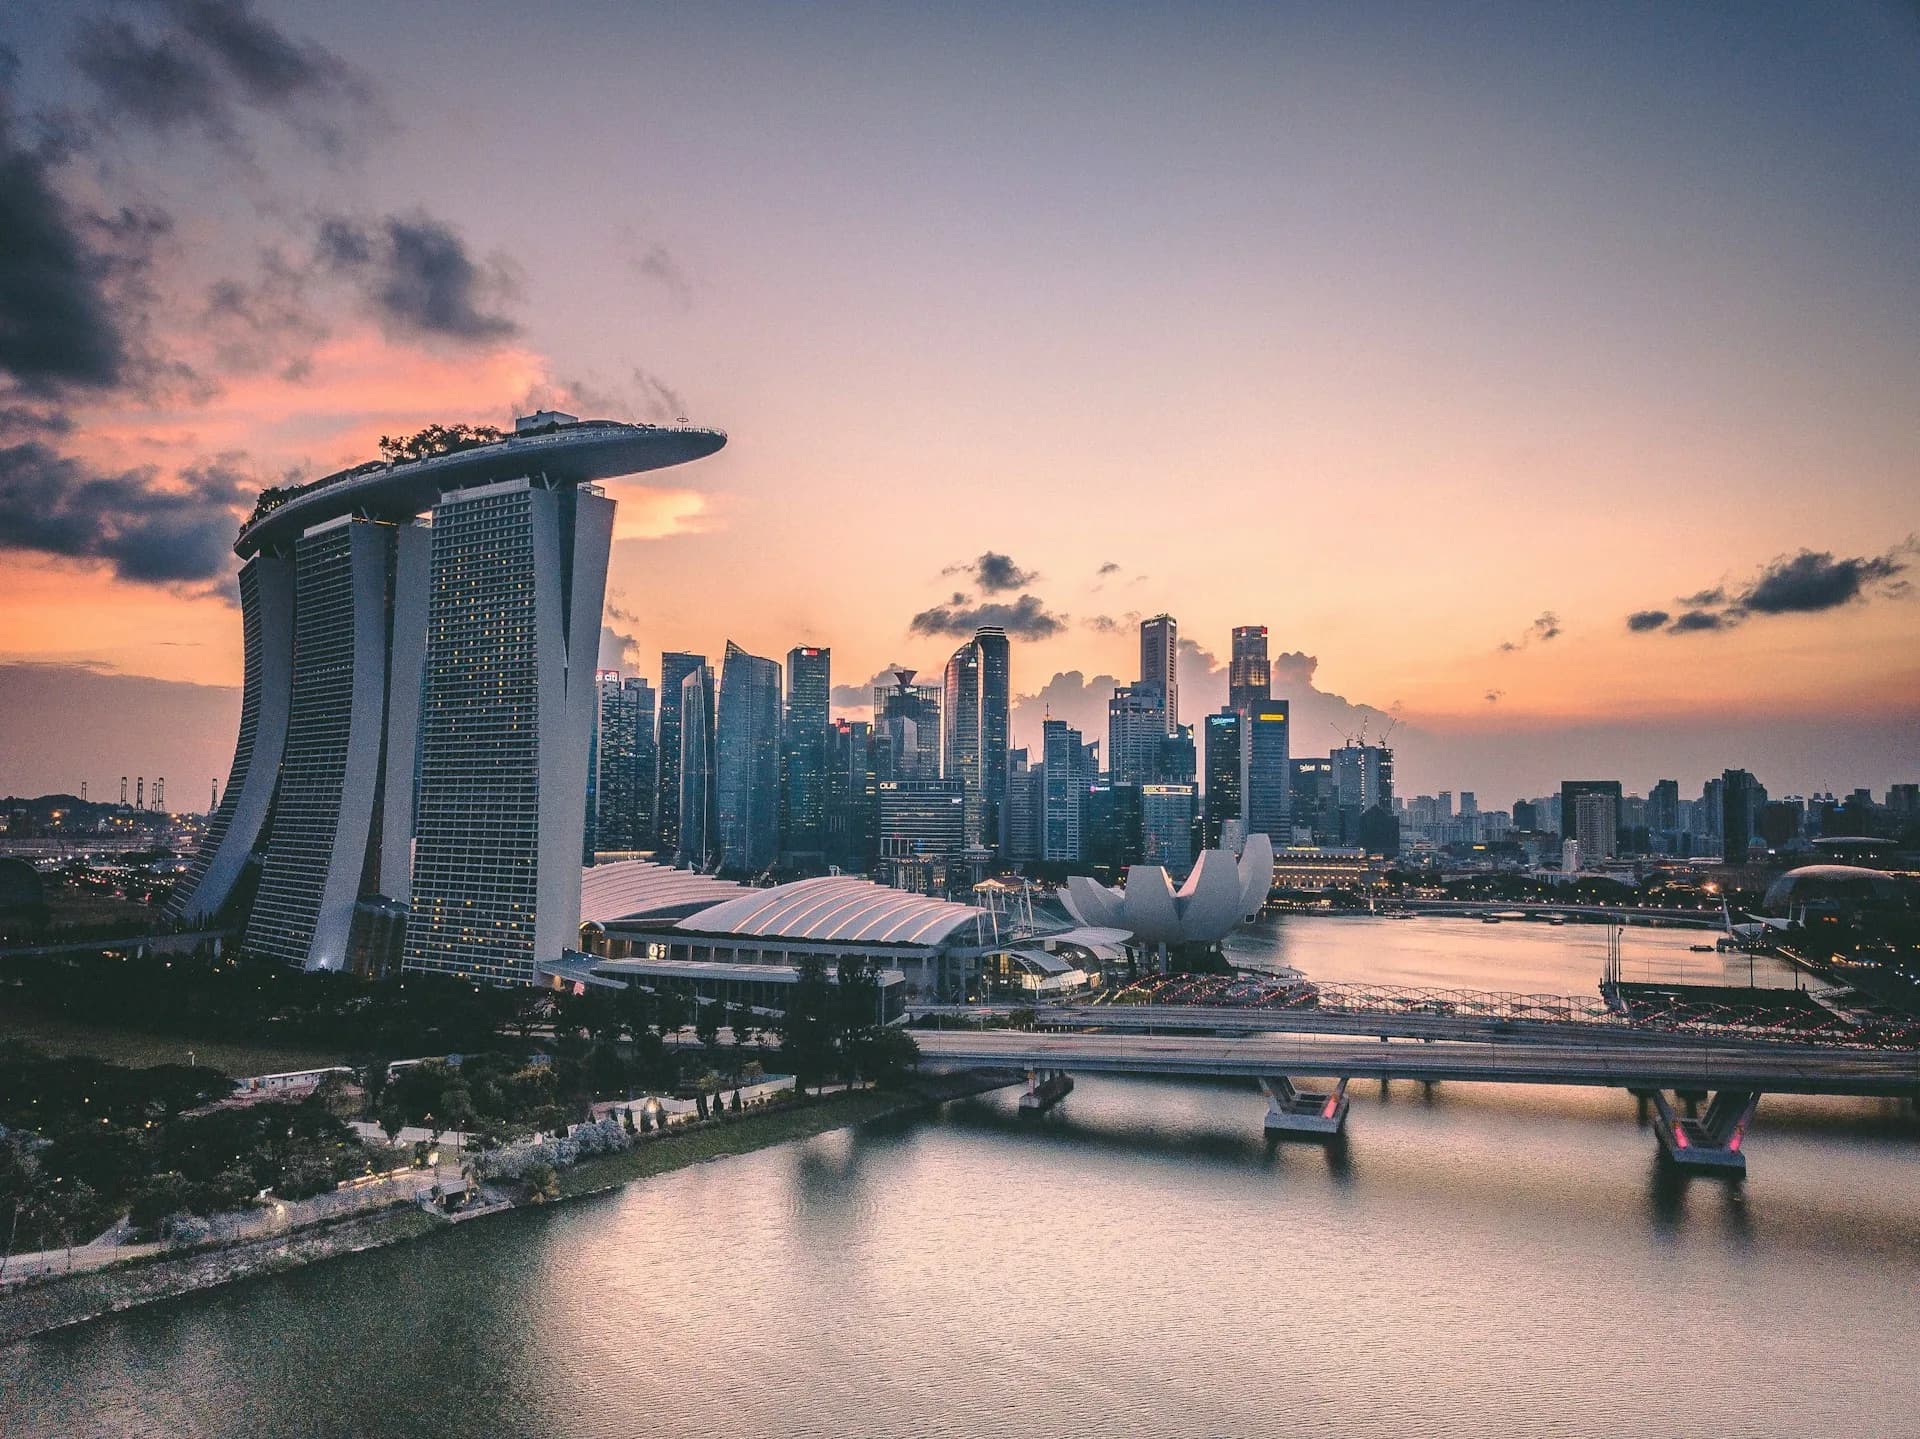

Singapore
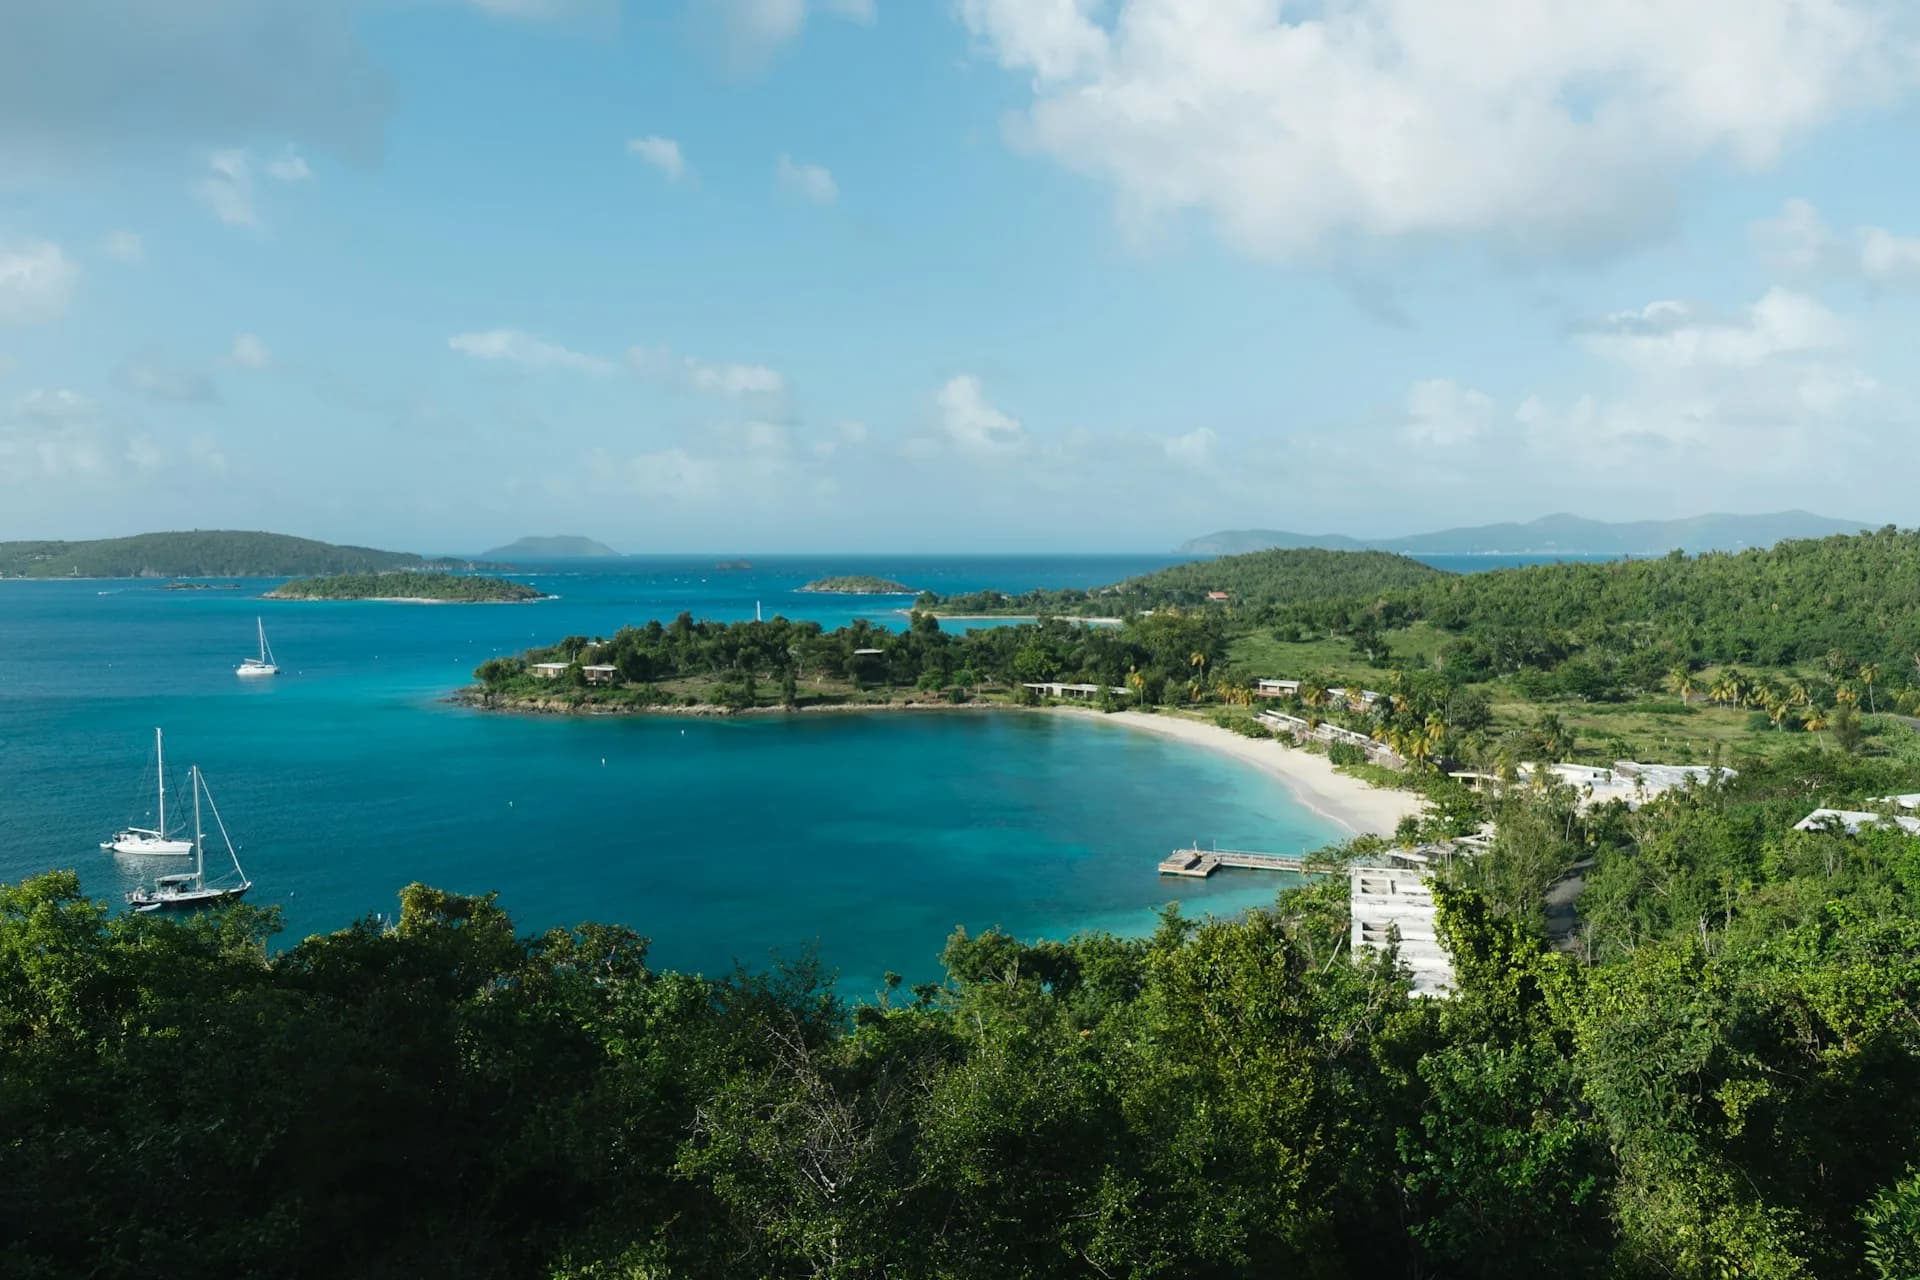

Antigua & Barbuda
Americans are subject to US tax on worldwide income regardless of where they live. Investment migration does not by itself reduce US tax liability. The two paths to actual US tax exit are (a) renunciation under IRC §877A — which triggers an exit tax for covered expatriates and is irreversible — or (b) maintenance of US citizenship while relocating to a treaty jurisdiction that reduces double-taxation through the foreign earned income exclusion (~$130K/yr in 2026), housing exclusions, and the foreign tax credit. Most US clients use investment migration for mobility and lifestyle, not tax exit. Renunciation candidates should engage tax counsel 18–24 months before filing.
The US permits dual citizenship — Americans can hold a Maltese, Caribbean, or Portuguese passport without losing US citizenship. FATCA reporting obligations follow Americans to every jurisdiction; foreign banks must report US-person accounts to the IRS, and many banks restrict services to US citizens. GILTI affects Americans with controlled foreign corporations regardless of residency. Renouncing US citizenship triggers IRS Form 8854 + potential exit tax for individuals over $2M net worth or $190K average annual tax liability over the prior 5 years.
Speak to a senior adviser
Not Sure Which Programme to Choose?
Book a one to one video consultation. We look at your goals, family and budget, then set out which programmes fit you, with the costs, timelines and next steps.
- Confidential, covered by an NDA
- Led by a senior adviser
- Final price shown before you book
Programme Review
You review your booking and pay securely on the next step.
Frequently asked questions
Can I keep my US citizenship and add a second passport?
Yes — the US permits dual citizenship. Most CBI and naturalisation programmes do not require renunciation of prior nationality.
Does Investment migration reduce my US tax liability?
Not by itself. Americans pay US tax on worldwide income regardless of residency. Tax exit requires either renunciation (with exit-tax considerations) or treaty-based reductions while maintaining US citizenship.
What is the exit tax for renouncing Americans?
IRC §877A exit tax applies to "covered expatriates" — generally those with net worth over $2M or 5-year average tax liability over $190K. The tax treats the renouncer as having sold all worldwide assets at fair market value on the day before renunciation.
Which programme is most popular among American clients?
Caribbean CBI (St. Kitts, Antigua, Dominica) for fast travel-mobility passports. UAE Golden Visa for substance-based tax positioning while retaining US citizenship. Portugal Golden Visa for the EU citizenship pathway.
Will I lose my current citizenship?
It depends on the law of your current country. Some allow dual citizenship freely, others restrict it or require permission. Take advice before you apply.
Which programmes are open to my nationality?
Eligibility depends on each programme. Some exclude certain nationalities or apply extra checks. The programmes on this page are suggestions; confirm eligibility for your nationality on each programme page or with an advisor.
Explore further
Programmes, guides, insights and tools related to this page.
More on investment migration for American citizens
American clients typically arrive at investment migration with one of three motivations: travel-mobility (a passport that doesn't carry US politics into immigration queues), tax-residency optimisation (substance-based relocation while retaining or renouncing US citizenship), and multi-generational planning (EU rights for children and grandchildren). Each motivation maps to a different stack. Travel-mobility is usually a Caribbean CBI — fast, no relocation required, $250K all-in. Tax positioning is UAE Golden Visa with documented substance, often paired with a Caribbean second passport for the mobility hedge. EU rights for descendants is Portugal Golden Visa (5-year naturalisation) or Malta CBI (direct citizenship). The decision matrix is usually narrowed in the first 60 minutes of a senior-advisor consultation: renouncement candidates and high-substance relocators want Malta or UAE; everyone else wants the Caribbean.